Frasers Centrepoint Trust (FY2016Q1) | DPU in previous vs current: $0.114 -> $0.116 EPS in previous Q1 vs current: $0.02963 -> $0.03039 Price in previous vs current: $1.87 -> $2.00 Yield in previous vs current: 6.2% -> 5.8% BV in previous vs current: $1.91-> $1.91 Revenue was stagnant, but a cut in expenses manage to inch up net income and DPU slightly. Woodlands Regional Hub in 2020, Northpoint City in the next 18 months and Downtown Line 3 will bring massive crowd and growth to their top 3 malls. AEI began in March at Northpoint, temporarily affecting occupancy. |
Super Group (FY2016Q1) | EPS in previous vs current: $0.0617 ->$0.0424 EPS in previous Q1 vs current: $0.122 -> 0.104 DPU in previous vs current: $0.031 -> $0.023 Price in previous vs current: $0.73 -> $0.90 Yield in previous vs current: 3.2% -> 2.5% BV in previous vs current: $0.468 -> $0.462 Revenue are stable while profits after tax fell another 15%, mostly due to forex and higher tax. Sales in SEA is ok but china seems to be weakening. The reasons for holding remains the same as before - strong operating cash flow and balance sheet with good margins. Assuming 4 cents earnings, the P/E is 22.5 which is quite high - not a good time to add. No turnaround in sight so this will be in the freezer for a while. |
China Merchant Pacific Holdings (FY2016Q1) | EPS (HKD) in previous vs current: $0.6731 -> $0.4376 EPS (SGD) in previous vs current: $0.12 -> $0.08 EPS (HKD) in previous Q1 vs current: $0.1197 -> $0.0907 DPU in previous vs current: $0.07 -> $0.07 Price in previous vs current: $0.78 -> $0.85 Yield in previous vs current: 9% -> 8.2% BV (HKD) in previous vs current: $0.532 -> $0.544 Revenue increases 28% while profits is up 15%. However, EPS dropped over 25% for the quarter; That's around 1.57 cents SGD. If we annualized Q1 profits, it is just 6.28 SGD cents. If it doesn't improve significantly, I doubt they can sustain the 7cents dividends payout. Afternote: Takeover at $1.02. Will let it go. |
Sembcorp Industries (FY2016Q1) | EPS in previous vs current: $0.443 -> $0.292 EPS in previous Q1 vs current: $0.079 -> 0.0542 DPU in previous vs current: $0.11 -> $0.11 Price in previous vs current: $2.5 -> $2.7 Yield in previous vs current: 4.4% -> 4.0% BV in previous vs current: $3.6 -> $3.6 (~$3.3 excl. pref shares) Continue its downturn with net profits plunging 25%, ROE dropping further to 6.7%. Interest cover has fallen from 9.7 to a dangerous 3.6 times! Stable performance for Utilities segment with profit going up 1% and now making up 72% of net profits. Singapore under pressure but overseas contributions are making up for it; India power plant and other energy investments expect to drive growth. Marine is "gone case" with profits dropping another 48%. Managment confident provisions has taken into account of Sete Brazil bankruptcy. |
M1 (FY2016Q1) | EPS in 2014 vs 2015: $0.191 -> $0.191 EPS in previous Q1 vs current: $0.049 -> $0.045 DPU in previous vs current: $0.189 -> $0.153 Price in previous vs current: $2.3 -> $2.48 Yield in previous vs current: 6.6% -> 6.2% Bad results as PBT fell from 46M to 43M. Quarter EPS fell from 4.9 to 4.5 cents. Comforting news is the increase of fibre/mobile customers by ~20K total, with market share remaining stable. While they are investing in many new initiatives like Smart City and Cloud offerings, it will take a few years for these to kick off. Management guidance seems to imply comparable profit for Y2016. |
Capital Commercial Trust (FY2016Q1) | DPU in 2014 vs 2015: $0.085 -> $0.086 DPU in previous Q1 vs current: $0.0212 -> $0.0219 Price in previous vs current: $1.3 -> $1.4 Yield in previous vs current: 6.6% -> 6.1% BV in previous vs current: $1.73 -> $1.72 Good and stable results, with 3.3% increase in DPU. Management has planned well against office supply headwinds, with ample 'reserves'. CCT joined the ranks of STI in this quarter. |
Accordia Golf Trust (FY2016) | DPU in previous vs current: $0.0571 (9M, 100%) -> $0.0663 (12M, 100%) Price in previous vs current: $0.56 -> $0.65 Yield in previous vs current: ~10% -> ~10% BV in previous vs current: $0.89 -> $0.89 Results are back on track thanks to a warmer winter. Assuming they can sustain 6 cents DPU per year, this is providing me a 10% yield. Still, their performance is highly subjected to unpredictable things like the weather, which makes sense for me to limit my exposure. My yield cow for the long term. |
ST Engineering (FY2016Q1) | EPS in previous vs current: $0.1705 -> $0.1705 EPS in previous Q1 vs current: $0.0417 -> $0.0353 DPU in previous vs current: $0.15 -> $0.15 Price in previous vs current: $2.84 -> $3.20 Yield in previous vs current: 5.3% -> 4.7% Disappointing 1st quarter with earnings plunging 15%! This is mainly due to Marine and Aerospace to a smaller extent. Management forsee a stronger 2nd half and maintain comparable profits guidance. |
Straits Times Index (FY2016) | Not Applicable |
Wednesday, June 15, 2016
Quarterly Results Review - 2016Q1

Wednesday, June 1, 2016
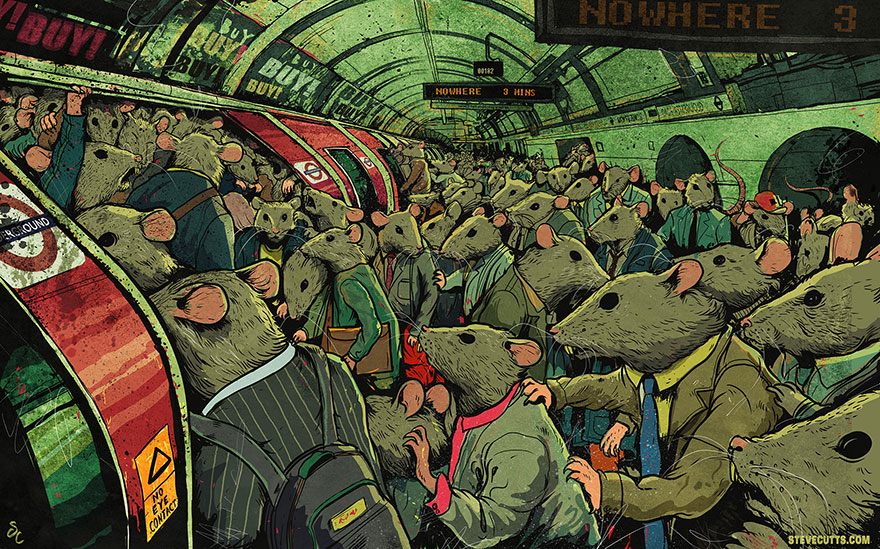
The Sad Truth of Today's World
When can we escape the rat race?
Do you want to be one of them until the day you die?
Or until your are 62, when the better 2/3 of your life is gone?
Sunday, May 1, 2016
Letter To Shareholders (2) - Performance Review 2016Q1
Welcome to the 2nd issue of ZZ Holdings Shareholders Letter.
Performance Highlights
Year 2016 started off with another round of sell-off, dragging the STI to a 5-year low of 2550. At that point, our equities portfolio was down as much as 15%. A strong rebound in March pushed us back into positive territory - fueled mainly by recovery of Super Group, Sembcorp and ST Engineering.
We are proud to announce that the company outperformed the market in 2016Q1, registering a 5.3% growth. This is a strong set of results, considering the STI continue to dip a further 3%.
In first quarter, we paid out over $500 in dividends, compared to just over $100 during the same period last year.
Operating Income - Record Revenue
In the 1st quarter of 2016, the company attained record revenue - roughly 22% higher than the same period last year. This is mainly attributed to higher than expected bonus in March, as well as unexpected windfall during the CNY season.
While we are pleased with the results, we do not expect such level of income to recur in the subsequent years.

Expenses for the quarter was 32% lower year on year - largely due to the absence of one-off big purchase (mattress) in Feb 2015. On the other hand, expenses were much higher in March 2016 due to the purchase of Daskey Keyboard, higher apparel and restaurant expenses.
If we exclude all one-time purchases, our expenses would be about 7% higher.

Opportune Trade In ST Engineering (STE)
We took advantage of the bear and brought STE during the January lows. While the initial plan was to hold it for the long term, we decided to capitalize on the opportunity to lock in the gains for our portfolio. This is in consideration that we have unlisted STE securities, and will continue to profit even if it continues its uptrend.
Overall, we held on to the stock for 2+ months and profited roughly 3 years of STE dividends. We believe there will be opportunities to buy back this defensive conglomerate for a lower price in the near future, or at least within the next 2 years.
Financial Accounts - Preparing For The Future
In March, we setup a Citibank Maxigain Account - which grants an interest of 80% of SIBOR + Step Up to 1.2%. Given the trend of rising SIBOR rates, this account has the potential to generate more than 2% risk free interest in the future. These are extremely attractive rates (for cash holdings) in exchange for a slight dip in our short term interest income.
Following that, we setup a Standard Chartered Securities (SCB) account, paving the way to overseas exposure. Our plan is to eventually grow our business beyond Singapore via the IWDA (World Index). As of now, the board is still deciding between using SCB or Interactive Brokers - this is a long-term plan and more details will be announced as we finalize the strategy.
Finally, we added CIMB Cash Upfront to our repertoire. This account cuts both buying and selling commission to 0.12% (from 0.25%), substantially reducing our future transaction costs.
Outlook
Our main revenue source continue to remain uncertain. We will work to find a replacement as soon as possible. Meanwhile, we are actively managing costs - the board do not expect expenses this year to exceed 2015, given that we have made most of our big purchases last year.
Quarter 2 will be a strong dividend period, with a vast majority of our holdings going XD. At the same time, we will look to accumulate more bargains to grow our passive income.
Performance Highlights
Year 2016 started off with another round of sell-off, dragging the STI to a 5-year low of 2550. At that point, our equities portfolio was down as much as 15%. A strong rebound in March pushed us back into positive territory - fueled mainly by recovery of Super Group, Sembcorp and ST Engineering.
We are proud to announce that the company outperformed the market in 2016Q1, registering a 5.3% growth. This is a strong set of results, considering the STI continue to dip a further 3%.
In first quarter, we paid out over $500 in dividends, compared to just over $100 during the same period last year.
Operating Income - Record Revenue
In the 1st quarter of 2016, the company attained record revenue - roughly 22% higher than the same period last year. This is mainly attributed to higher than expected bonus in March, as well as unexpected windfall during the CNY season.
While we are pleased with the results, we do not expect such level of income to recur in the subsequent years.

Expenses for the quarter was 32% lower year on year - largely due to the absence of one-off big purchase (mattress) in Feb 2015. On the other hand, expenses were much higher in March 2016 due to the purchase of Daskey Keyboard, higher apparel and restaurant expenses.
If we exclude all one-time purchases, our expenses would be about 7% higher.

Opportune Trade In ST Engineering (STE)
We took advantage of the bear and brought STE during the January lows. While the initial plan was to hold it for the long term, we decided to capitalize on the opportunity to lock in the gains for our portfolio. This is in consideration that we have unlisted STE securities, and will continue to profit even if it continues its uptrend.
Overall, we held on to the stock for 2+ months and profited roughly 3 years of STE dividends. We believe there will be opportunities to buy back this defensive conglomerate for a lower price in the near future, or at least within the next 2 years.
Financial Accounts - Preparing For The Future
In March, we setup a Citibank Maxigain Account - which grants an interest of 80% of SIBOR + Step Up to 1.2%. Given the trend of rising SIBOR rates, this account has the potential to generate more than 2% risk free interest in the future. These are extremely attractive rates (for cash holdings) in exchange for a slight dip in our short term interest income.
Following that, we setup a Standard Chartered Securities (SCB) account, paving the way to overseas exposure. Our plan is to eventually grow our business beyond Singapore via the IWDA (World Index). As of now, the board is still deciding between using SCB or Interactive Brokers - this is a long-term plan and more details will be announced as we finalize the strategy.
Finally, we added CIMB Cash Upfront to our repertoire. This account cuts both buying and selling commission to 0.12% (from 0.25%), substantially reducing our future transaction costs.
Outlook
Our main revenue source continue to remain uncertain. We will work to find a replacement as soon as possible. Meanwhile, we are actively managing costs - the board do not expect expenses this year to exceed 2015, given that we have made most of our big purchases last year.
Quarter 2 will be a strong dividend period, with a vast majority of our holdings going XD. At the same time, we will look to accumulate more bargains to grow our passive income.
Friday, April 1, 2016
Bitter First, Sweet Later
Sharing one amazing piece I come across from our very own government board: The $5-latte problem.
I suggest reading through it before continuing further.
...
Essentially the article presents 2 common school of thought to retirement:
1) Work and save reasonably for 30+ years.
2) Focus all energy to increase income, and spend freely to reward yourself.
Both are perfectly viable strategy.
And then, somewhere along the way, a small group of people "discovered" a third method.
In the meantime, you live in a simple and self-sufficient manner, spending money as efficiently as possible. This way of living is not about extreme miserliness, but more about reorienting yourself with what is meaningful in life that happens to be free or costs little."

I suggest reading through it before continuing further.
...
Essentially the article presents 2 common school of thought to retirement:
1) Work and save reasonably for 30+ years.
2) Focus all energy to increase income, and spend freely to reward yourself.
Both are perfectly viable strategy.
And then, somewhere along the way, a small group of people "discovered" a third method.
"At age 25, instead of thinking of saving just S$500 a month like everyone else, you can go all out. You
draw on all the resources of youth and time to accumulate as big a
stash as you can while you're young, such that you hit a six-digit sum
in your 30s and use the power of compounding to do the rest.
In the meantime, you live in a simple and self-sufficient manner, spending money as efficiently as possible. This way of living is not about extreme miserliness, but more about reorienting yourself with what is meaningful in life that happens to be free or costs little."
This sums up the essence of my saving strategy.
Let
me strip it down further using the example in the article. Assuming
same rate of return, which one gives you more money in the end?
1) Saving $500/mth for 30+ years.
2) Saving $2500/mth for the first 5 year of your working life, then never saving a single cent for the next 25 years.
...
Yep! Scenario 2 results in a higher retirement nest!!! Doesn't that sound unbelievable and counter-intuitive?
The absolute numbers are not what's important. The message here is to demonstrate the power of time and compound interest.
...
"The philosophy behind this idea is known in Internet circles as FIRE, or financial independence and retiring early."
I have shared many bloggers in previous posts who have achieved FIRE, and the article introduced even more local and overseas ones.
Need more inspiration/living proof? Here are 5 active bloggers drawing 5 digits passive income a year.
Need more inspiration/living proof? Here are 5 active bloggers drawing 5 digits passive income a year.
I
am working hard to follow in their footsteps - Not as extreme as some
of them, but at a pace that I am comfortable with. (I still drink bubble
tea, eat restaurants, buy expensive gadgets... occasionally)
That day can't arrive soon enough.

Monday, March 21, 2016
The Most Valuable Thing Money Can Buy
Came across another awesome article from My Money & Me about the importance of savings, and benefits of living a minimalist life.
“The most valuable thing money can buy is freedom from having to worry about money.”
I share many beliefs with the author, and I'm glad there is someone who can put across the point so well. If you hadn't notice - In Singapore, you must be a freaking "weirdo" if you have no desire to buy a car. You must be living a miserable life if you do not consume much. You must not have much ambition if you do not want to buy or upgrade to a Condo/big house.
Don't get me wrong. It is not that I do not have desire for such things - it's just that I do not see how they are worth their prices.
We work on a job we hate, so that we can buy a car to more easily get to work?
We spend years of our working life to upgrade to a bigger and better house, but leave the house vacant most of the time because we are at work?
How does that make sense?
If it doesn't, then maybe you are simply making luxurious purchases to prove something. To prove how "successful" you are, or maybe just to fit into society norms.
Do you know if you save just 5% more of your income each month, you can cut your working years by as much as 4-8 years? [See links below]
How much % of your income does a car installment cost you? 20%? You are willing to extend your retirement by 20 years just to own a car?
Remember that when you are purchasing a liability for, say $100K. You are not only losing that $100K. You are losing all the compounded money that could have grown out of that $100K for the REMAINING of your life (40+ years).
To me, their costs are far too high. I will consider them if one day I strike $10M toto and their costs become negligible compare to my networth. Until then, I find such things frivolous.
--------------------------------------------------------------------------------------------------------------------------
"If you are spending 100% (or more) of your income, you will never be prepared to retire, unless someone else is doing the saving for you (wealthy parents, social security, pension fund, etc.). So your work career will be Infinite.
If you are spending 0% of your income (you live for free somehow), and can maintain this after retirement, you can retire right now. So your working career can be Zero.
In between, there are some very interesting considerations. As soon as you start saving and investing your money, it starts earning money all by itself. Then the earnings on those earnings start earning their own money. It can quickly become a runaway exponential snowball of income. As soon as this income is enough to pay for your living expenses, while leaving enough of the gains invested each year to keep up with inflation, you are ready to retire."
Mr Money Mustache
--------------------------------------------------------------------------------------------------------------------------
"But to some people, wealth is the most important thing in their life, and they are forever endeavouring to accumulate more wealth. Whenever they gain more, it is never enough, and they then plan or plot to gain even more. It is an endless pursuit in self-gratification with no meaningful purpose in life.
Happiness, in whatever form one sees it, becomes more elusive the harder one tries to pursue it.
That’s why my personal aim is much more realistic: All I ask for is calmness and contentment. These at least are partially within my control."
Pursuit of Happiness (Dr Lee Wei Ling)
“The most valuable thing money can buy is freedom from having to worry about money.”
I share many beliefs with the author, and I'm glad there is someone who can put across the point so well. If you hadn't notice - In Singapore, you must be a freaking "weirdo" if you have no desire to buy a car. You must be living a miserable life if you do not consume much. You must not have much ambition if you do not want to buy or upgrade to a Condo/big house.
Don't get me wrong. It is not that I do not have desire for such things - it's just that I do not see how they are worth their prices.
We work on a job we hate, so that we can buy a car to more easily get to work?
We spend years of our working life to upgrade to a bigger and better house, but leave the house vacant most of the time because we are at work?
How does that make sense?
If it doesn't, then maybe you are simply making luxurious purchases to prove something. To prove how "successful" you are, or maybe just to fit into society norms.
Do you know if you save just 5% more of your income each month, you can cut your working years by as much as 4-8 years? [See links below]
How much % of your income does a car installment cost you? 20%? You are willing to extend your retirement by 20 years just to own a car?
Remember that when you are purchasing a liability for, say $100K. You are not only losing that $100K. You are losing all the compounded money that could have grown out of that $100K for the REMAINING of your life (40+ years).
To me, their costs are far too high. I will consider them if one day I strike $10M toto and their costs become negligible compare to my networth. Until then, I find such things frivolous.
--------------------------------------------------------------------------------------------------------------------------
"If you are spending 100% (or more) of your income, you will never be prepared to retire, unless someone else is doing the saving for you (wealthy parents, social security, pension fund, etc.). So your work career will be Infinite.
If you are spending 0% of your income (you live for free somehow), and can maintain this after retirement, you can retire right now. So your working career can be Zero.
In between, there are some very interesting considerations. As soon as you start saving and investing your money, it starts earning money all by itself. Then the earnings on those earnings start earning their own money. It can quickly become a runaway exponential snowball of income. As soon as this income is enough to pay for your living expenses, while leaving enough of the gains invested each year to keep up with inflation, you are ready to retire."
Mr Money Mustache
--------------------------------------------------------------------------------------------------------------------------
"But to some people, wealth is the most important thing in their life, and they are forever endeavouring to accumulate more wealth. Whenever they gain more, it is never enough, and they then plan or plot to gain even more. It is an endless pursuit in self-gratification with no meaningful purpose in life.
Happiness, in whatever form one sees it, becomes more elusive the harder one tries to pursue it.
That’s why my personal aim is much more realistic: All I ask for is calmness and contentment. These at least are partially within my control."
Pursuit of Happiness (Dr Lee Wei Ling)
Monday, March 7, 2016
Quarterly Results Review - 2015Q4
From this year onward, I shall commit to writing brief quarterly results review for several reasons:
1. Regular evaluation ensures the company still have fundamentals and meets my portfolio goals.
2. Keep a long-term record of basic valuation metrics to help future decisions.
3. A deterrence to myself rashly purchasing businesses I do not understand.
4. A good training for increasing my investment aptitude.
I will be using the calendar year to perform this review. (2015Q4 will be reviewing the results from Sep 2015 to Dec 2015)
For this time only, I will use rough figures from the previous year. Subsequently I will use the previous quarter's numbers. For prices, I will just use any value in the period when I was writing the update.
These review will be very brief and only highlight the most important developments for that company. This is so that I have the motivation/time to regularly update them.
-------------------------------------------------------------------------------------------------------------------------
1. Regular evaluation ensures the company still have fundamentals and meets my portfolio goals.
2. Keep a long-term record of basic valuation metrics to help future decisions.
3. A deterrence to myself rashly purchasing businesses I do not understand.
4. A good training for increasing my investment aptitude.
I will be using the calendar year to perform this review. (2015Q4 will be reviewing the results from Sep 2015 to Dec 2015)
For this time only, I will use rough figures from the previous year. Subsequently I will use the previous quarter's numbers. For prices, I will just use any value in the period when I was writing the update.
These review will be very brief and only highlight the most important developments for that company. This is so that I have the motivation/time to regularly update them.
-------------------------------------------------------------------------------------------------------------------------
| Frasers Centrepoint Trust (FY2015) | DPU in previous vs current: $0.114 -> $0.116 Price in previous vs current: $1.78 -> $1.87 Yield in previous vs current: 6.4% -> 6.2% BV in previous vs current: $1.77 -> $1.91 Woodlands Regional Hub in 2020, Northpoint City in the next 18 months and Downtown Line 3 will bring massive crowd and growth to their top 3 malls. In the short term, DPU may be affected due to asset enhancements (i.e occupancy drop) at Northpoint, their 2nd biggest mall. |
| Super Group (FY2015) | EPS in previous vs current: $0.0617 ->$0.0424 DPU in previous vs current: $0.031 -> $0.023 Price in previous vs current: $1.73 -> $0.73 Yield in previous vs current: 1.8% -> 3.2% BV in previous vs current: $0.446 -> $0.468 Results continue to disappoint with EPS falling over 30%. Its saving grace lies with its robust operating cash flow, improved margins (mainly from lower material costs) and strong balance sheet. Management and analysts are betting on China growth (which is showing some momentum) and new products innovation. |
| EPS (HKD) in previous vs current: $0.6731 -> $0.4376 EPS (SGD) in previous vs current: $0.12 -> $0.08 DPU in previous vs current: $0.07 -> $0.07 Price in previous vs current: $1.0 -> $0.78 Yield in previous vs current: 7% -> 9% BV (HKD) in previous vs current: $0.586 -> $0.532 Quite bad results with payout ratio skyrocketing from 63 to 96%. Management gives a challenging outlook, but still believe in the long-term growth of China toll road industry. They are proposing to adopt scrip dividends to save cash, but dilution will not benefit minority shareholders. If there's no turnaround, they will not be able to sustain 7c dividends next year. I may look to off-load this should the chance arises. |
| Sembcorp Industries (FY2015) | EPS in previous vs current: $0.443 -> $0.292 DPU in previous vs current: $0.16-> $0.11 Price in previous vs current: $4.8 -> $2.5 Yield in previous vs current: 3.3% -> 4.4% BV in previous vs current: $3.15 -> $3.6 (~$3.0 excl. pref shares) Expected horrible results with Marine provisions dragging down the entire group. Even Utilities, to my dismay, registered lower profits (-19%) if you exclude 1 time divestment. Singapore Utilities are facing immense pressure as well. ROE plunged from 15.2% to 9.4%. Interest cover more than halved from 20.8 to 7.2 times and debt ballooned by $2 billion. Overall it's very very jialat. Only hope is on overseas contribution to step up from 2016 onwards. |
| M1 (FY2015) | EPS in previous vs current: $0.191 -> $0.191 DPU in previous vs current: $0.189 -> $0.153 Price in previous vs current: $3.51 -> $2.3 Yield in previous vs current: 5.4% -> 6.6% Dividends were slashed to their minimum payout of 80%, but luckily not due to reduced earnings. Company is conserving $ to bid for the new spectrum and "fight" against the 4th Telco. When they come onboard, EPS might fall by 10% as an estimate, consequently resulting in a 6% yield. Painful reminder to myself to evaluate the payout ratio. Note that after looking at Starhub results, M1's does not look as bad. |
| Capital Commercial Trust (FY2015) | DPU in previous vs current: $0.085 -> $0.086 Price in previous vs current: $1.55 -> $1.3 Yield in previous vs current: 5.5% -> 6.6% BV in previous vs current: $1.73 -> $1.73 No negative or positive surprises. Do not forsee office-supply glut in 2016 to negatively impact DPU. Growth may stagnant but should not fall. |
| Accordia Golf Trust (9M2015) | DPU in previous vs current: $0.0571 (9M, 100%) -> $0.0232 (6M, 90%) Price in previous vs current: $0.63 -> $0.56 Yield in previous vs current: 7% -> ~10% (If 100% distribution) BV in previous vs current: $0.87 -> $0.89 After a disastrous 2Q, results were a huge positive surprise with 17% more profits compare to previous year 3Q, mainly due to good weather and strengthening yen. Management also decide to "release" back previous retained 10% distributions back to shareholders. Costs were controlled and visitors/utilization remain stable. Overall great results but what bother me is that the main catalysts aren't exactly recurring or dependable. To take a conservative stance with 90% distributions and a worst case DPU of $0.04, yield is 7.1%, which provides a good buffer. |
| ST Engineering (FY2015) | EPS in previous vs current: $0.1706 ->$0.1705 DPU in previous vs current: $0.15 -> $0.15 Price in previous vs current: $3.6 -> $2.84 Yield in previous vs current: 4.2% -> 5.3% Given the previous guidance, results were slightly better than expected. They managed to achieve comparable profits despite being dragged down by Marine. Management expects 2016 profits to be comparable. |
| Straits Times Index (FY2015) | DPU in previous vs current: $0.098 -> $0.102 Price in previous vs current: $3.4 -> $2.6 Yield in previous vs current: 2.9% -> 3.9% Half year dividends increased from 0.048 to 0.051! P/E of 10.54 and P/Cashflow of 9 makes it near historical low. This is the deal of the decade right here. |
Tuesday, February 23, 2016
Letter To Shareholders (1) - Performance Review 2015Q4
We
are proud to present the 1st issue of ZZ Holdings Shareholders Letter, a
brand new effort to bring regular updates to its shareholders. ZZ
Holdings is a private investment holding company aimed at achieving long
term financial growth and capital protection for its investors. We
achieve this with our unique 3-pillar management strategy - strong
cashflow generation, long-term sustainability and fortress balance
sheet.
Strong Cashflow Generation
We
invest in companies with predictable cash-flow and strong dividends
record. A steady cash flow offsets expenses in good times, and sustain
the company in bad times without dipping into reserves.
Long Term Sustainability
We
invest with a long-term view, avoiding market speculation and short
term economic trends. We invest in quality companies that will still be
profitable far in the future, and limit our exposure to cyclical
industries and unproven startups.
Fortress Balance Sheet
We
never overstretch, always maintaining a fortress-like balance sheet to
give investors peace of mind and more importantly, capitalize on
downswings and opportunities. Our reserves grants us exceptional holding
power, ensuring the company can withstand any crisis and emerge
stronger.
-----------------------------------------------------------------------------------------------------------------------
Streamlining Operations
In
late 2015 and early 2016, the company streamlined its financial
accounts by closing OCBC Bonus+ (which pared down its interest
significantly) and other legacy savings accounts. CIMB StarSaver was
also vacated in favor of the higher interests and no frills FastSaver.
Following this, our funds are now parked in CIMB FastSaver and OCBC360,
generating risk-free interest of 1% to 1.75%.
The
company also applied for its first credit facility, the AMEX, in Nov
2015. AMEX provides a 1.5% true cashback rebate, and we are already
reaping its benefits.
Performance Highlights
2015
was a bear market year, with the STI losing over 13% of its value.
Comparatively, the company made losses of 12.2%. In light of its 5-year
low valuation, we brought into the STI for the first time in 2015Q4 as
we believe it represents the most prudent investment at the moment.
Going forward, the STI is expected to become the core holding in the
company, supplemented by other higher yielding investments.
The
board is glad to announce that over $2400 total dividends has been paid
out in 2015, our first full year since listing. This is in line with our initial forecast of $200/month in our prospectus.
Outlook
The
global economy and market is expected to remain volatile, with possible
recession looming in the horizon. The company may also lose its main
source of revenue in 2016Q2. Despite the challenging outlook, ZZ
Holdings remains committed to actively pursue a replacement that will
enhance shareholder value.
Subscribe to:
Posts (Atom)